

AI summary
- Aviva’s new sterling tokenized share class starts with £50 million; more than £86 million is invested across its two tokenized offerings, not the underlying fund’s £22 billion.
- The OCC’s stablecoin framework takes effect on January 18, 2027. Issuer interest is prohibited; certain third-party rewards remain conditional, not blanket-approved.
- The SEC’s tokenized-securities guidance describes a conditional path for permissioned venues, not an endorsement of XRPL or unrestricted secondary trading.
- Cross River’s RLUSD integration connects stablecoin capabilities with existing banking APIs and payment rails; the announcement does not establish current transaction volumes.
- Infrastructure adoption can support the ecosystem without automatically creating XRP demand. The relevant evidence is actual capital, transaction activity and native-token utility.
Institutional adoption does not always arrive with a spectacular announcement. Sometimes, the more meaningful shift is a conventional asset manager putting an existing, regulated investment product onto blockchain infrastructure and committing real capital to it.
That is the story at Aviva Investors today. Meanwhile, U.S. regulators are defining the operating conditions for stablecoins and tokenized securities. Taken together, these moves help clarify where the XRP Ledger and Ripple’s financial infrastructure fit into the emerging financial system — and where XRP’s role still needs to be demonstrated.
Aviva Brings a Second Money Market Fund Share Class to XRPL
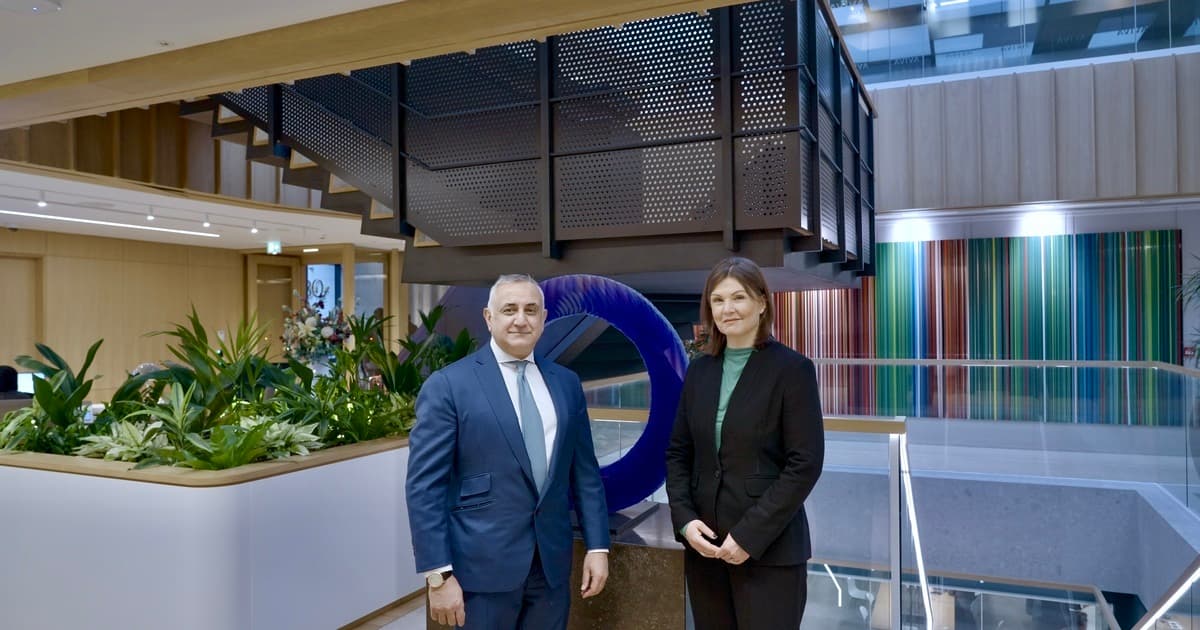 Image credit: Aviva Investors–Ripple partnership photograph, Investment Week (February 2026).
Aviva Investors and Ripple announced on October 26 the launch of a tokenized share class for Aviva’s Sterling Liquidity Fund on the XRP Ledger. The underlying fund manages approximately £22 billion, making it Aviva’s largest fund. But that does not mean £22 billion has moved onto XRPL.
The amount initially invested in the new tokenized share class is £50 million. Combined with Aviva’s tokenized U.S. dollar fund share class, launched in July, the firm reports more than £86 million invested across its two tokenized offerings.
That distinction matters. The fund’s total assets under management describe the size of the traditional investment vehicle; the tokenized share-class figures describe the actual capital committed to the new structure.
The arrangement is designed to maintain the familiar protections and economics of an existing regulated fund while recording eligible investor holdings in tokenized form. BNY remains custodian of the underlying fund assets; Komainu supports digital-asset custody, and Licuido supplies tokenization technology. Ripple’s contribution is the infrastructure and partnership supporting issuance on XRPL.
For the XRP Ledger, this is more persuasive evidence of institutional adoption than a compatibility announcement or an exploratory pilot. A regulated asset manager is operating a second live tokenized fund product and expanding capital committed to that model.
For XRP itself, the connection is narrower. XRP is the network’s native asset, used for transaction fees and account reserves. The announcement does not establish that Aviva holds XRP as an investment, uses it as settlement liquidity, or creates proportional XRP demand from the fund’s total assets.
U.S. Stablecoin Rulemaking Gets More Concrete
On October 21, the Office of the Comptroller of the Currency finalized implementing rules associated with the GENIUS Act. The framework addresses reserve assets, redemption obligations, custody arrangements, licensing and the risk controls expected of payment-stablecoin issuers. The effective date is January 18, 2027.
A key distinction concerns yield. The rules prohibit issuers from paying interest simply for holding payment stablecoins, while providing room for certain third-party rewards and commercial arrangements that meet the relevant conditions. That is not the same as allowing an issuer to market a stablecoin as an interest-bearing deposit.
This is directly relevant to Ripple USD, or RLUSD. The product sits in an increasingly defined regulated-stablecoin market, where the credibility of reserves, redemption processes and distribution partnerships will be crucial to adoption. Regulatory clarity can make conversations with banks and payment companies easier, but compliance and commercial deployment still need to be demonstrated institution by institution.
The rulemaking also contemplates limited digital-asset holdings for network fees in certain circumstances. XRP could potentially serve that function for eligible XRPL activity, but the regulatory language is not evidence of a new institutional XRP allocation or broad payment flow.
SEC Opens a Conditional Path for Tokenized Securities
The SEC issued guidance on October 20 addressing an innovation exemption for certain permissioned trading models involving tokenized securities. It outlines conditions and notification requirements for venues seeking to operate within the specified framework.
For tokenization providers, the signal is important: regulators are beginning to describe practical routes for bringing digital representations of securities into supervised market structures.
Yet this is a conditional regulatory pathway, not a blanket approval for every blockchain or tokenization product. It does not endorse XRPL specifically, and it should not be confused with permission for unrestricted secondary trading.
XRPL’s institutional features — including controls that can support regulated issuance and transfer — may make the ledger relevant to these discussions. Actual adoption still requires a regulated operator, a deployed product, liquidity and lawful market access.
Cross River and RLUSD: Distribution Beyond a Crypto Wallet
Cross River Bank’s recently announced integration of RLUSD into its banking infrastructure provides a separate view of how stablecoins can reach financial customers.
The bank described a model in which fintech clients could access stablecoin capabilities through its existing technology and API relationships, alongside conventional payment methods such as ACH, wires and real-time payment rails. XRPL support forms part of the announced integration.
That is a distribution story, not simply a token-listing story. If financial businesses can reach RLUSD through the same provider that supports their existing banking workflows, using a stablecoin may become an operational option rather than a separate crypto integration project.
The important caveats remain: the announcement followed earlier this month’s reporting, geographic availability is limited, and an integration does not reveal how much transaction volume is actually flowing through RLUSD on XRPL. Cross River cited roughly $2.5 billion in RLUSD market capitalization at the time and about $1 billion associated with XRPL; those are announcement-period figures rather than independently measured live values today.
What the Bigger Picture Tells Us
The emerging pattern connects three different pieces of financial infrastructure.
Aviva shows that fund ownership can be represented on a public ledger without replacing the conventional custodian or regulated investment structure. The OCC and SEC developments help define how issuers and market intermediaries may work with digital money and tokenized securities. Cross River demonstrates how a stablecoin can be integrated into banking distribution rather than confined to exchanges.
Ripple participates through different businesses and products, but those roles should not be merged. The company supplies enterprise relationships and technology; XRPL is the network; RLUSD is the dollar-denominated stablecoin; and XRP is the ledger’s native asset. Growth in one area can support the broader ecosystem without guaranteeing immediate demand for another.
The strongest institutional thesis is therefore about usable infrastructure: regulated assets, reliable custody, compliant access and financial applications that customers can reach. The investment case for XRP requires an additional, measurable bridge from that infrastructure to native-token usage.
Final Thoughts
Today’s headline is Aviva’s second tokenized fund share class, because it converts a previously announced relationship into a larger live deployment. The rules coming out of Washington matter for a different reason: they shape how similar products can scale.
For XRP holders, both are constructive developments to watch, but the useful measures are capital actually tokenized, real transaction activity, and evidence of native XRP utility — not the headline size of every institution entering the market.
Partner spotlight
Crypto and precious metals for your retirement
Buy XRP, XLM, gold & silver in a tax-advantaged IRA.
$100 funding bonus when you open and fund a new IRA or PCA.*
Get started*Terms and conditions apply.
Sources
https://www.occ.treas.gov/news-issuances/news-releases/2026/nr-occ-2026-92.html
https://www.occ.gov/news-issuances/bulletins/2026/bulletin-2026-50.html
https://www.sec.gov/rules-regulations/public-comments/4-927
Image credit: Aviva Investors–Ripple partnership photograph, Investment Week (February 2026).
https://www.investmentweek.co.uk/news/4525511/aviva-investors-ripple-partner-fund-tokenisation