
AI summary
- Ripple’s final OCC approval covers a national trust-bank structure for reserve administration and fiduciary custody—not a conventional retail bank or automatic XRP demand.
- Aviva has invested £50 million in its new tokenized sterling share class, bringing capital across two tokenized offerings above £86 million. The underlying £22 billion fund is not fully tokenized.
- Ripple Treasury’s new tools support always-on cash management and eligible RLUSD use. Naming existing customers does not establish that those companies use RLUSD or XRP.
- The OCC’s stablecoin rule takes effect on January 18, 2027. Direct issuer-paid interest or yield is prohibited; third-party arrangements depend on their specific circumstances.
- Issuer objections to tokenized equities highlight unresolved questions about ownership, permissions and market access that blockchain technology alone cannot settle.
- Institutional infrastructure adoption is distinct from XRP value accrual. The next test is measurable native-token liquidity, bridging, collateral or other use at scale.
Ripple and the XRP Ledger are moving further into the infrastructure of regulated finance. Three developments announced on October 26 highlight different parts of that transition: a federal banking charter, a live tokenized investment product, and new tools for corporate cash management. The common thread is institutional access, not an immediate promise of XRP demand.
Ripple Receives Final OCC Approval for National Trust Bank
 Supplied editorial graphic from the approved Issue 031 PDF.
Ripple has received final approval from the Office of the Comptroller of the Currency to charter Ripple National Trust Bank. This follows the conditional approval granted in December 2025 and gives Ripple a federally supervised trust-bank structure for specific institutional activities.
The bank's approved remit includes managing segregated reserves supporting RLUSD, acting as a collateral trustee for those reserves, and providing fiduciary digital-asset custody once it opens. RLUSD itself will continue to be issued by Standard Custody & Trust Company, Ripple's New York-regulated entity.
This is a meaningful regulatory milestone, but it is not the same as receiving permission to operate a conventional deposit-taking retail bank. For Ripple, the strategic gain is a stronger regulated foundation for reserve administration and custody. XRP exposure remains indirect: a trust charter does not, by itself, create transaction demand for XRP.
Aviva Expands Its Tokenized Liquidity Funds on XRPL
 Supplied editorial graphic from the approved Issue 031 PDF.
Aviva Investors launched a tokenized share class of its Sterling Liquidity Fund on October 26, using the XRP Ledger. The underlying Sterling Liquidity Fund manages approximately £22 billion, but that is the size of the overall traditional fund—not the amount tokenized.
Aviva has invested £50 million in the new tokenized share class. Together with its previously launched USD fund share class, the manager now reports more than £86 million invested across its two tokenized offerings.
The structure uses a digital-twin model: ownership can be represented on-chain while the existing fund and its regulatory protections remain intact. Komainu and Licuido supported the launch, with BNY Mellon serving as fund custodian.
This offers a concrete example of an established asset manager using XRPL for regulated investment-product infrastructure. It does not mean £22 billion has moved onto XRPL, or that investors must buy XRP to own the fund. The stronger long-term question is whether growing tokenized activity produces sustained settlement, liquidity and collateral demand on the network.
Ripple Treasury Introduces Always-On Corporate Cash Management
 Supplied editorial graphic from the approved Issue 031 PDF.
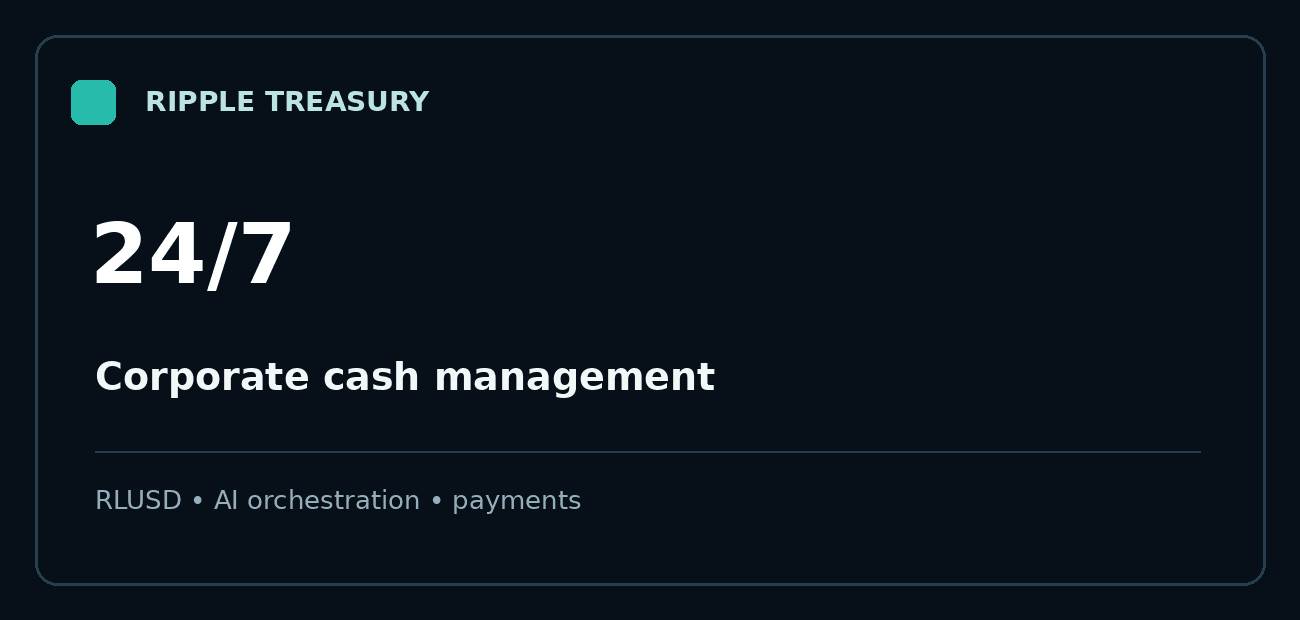
Ripple Treasury announced new orchestration tools and 24/7 Returns at Swell 2026. The platform combines traditional treasury workflows with digital payment rails, AI-assisted orchestration and the ability for eligible businesses to put operating cash to work beyond conventional banking hours, including through RLUSD.
Ripple named established treasury customers such as American Airlines, Subway and Adecco in describing the broader platform. Their inclusion does not establish that those companies already use RLUSD or XRP.
The significance is in bringing blockchain-enabled money movement into software corporate finance teams already understand. Whether RLUSD becomes a widely used treasury instrument will depend on actual deployments, distribution and economic incentives—not the announcement alone.
U.S. Stablecoin Rules Become More Concrete
On October 21, the OCC issued its final rule implementing provisions of the GENIUS Act, with an effective date of January 18, 2027. Among other provisions, the rule addresses the prohibition on payment of interest or yield by payment-stablecoin issuers directly to holders. Third-party arrangements are evaluated according to their facts and circumstances.
That distinction matters as issuers and platforms design stablecoin-linked financial products. For RLUSD, regulatory clarity could support institutional confidence, while limiting certain issuer-funded yield structures. It should not be read as blanket permission for every yield-bearing stablecoin arrangement.
Tokenized Equities Still Face Issuer Resistance
Reuters reported on October 23 that Wells Fargo, Arm, Intuit and other companies objected to tokenized versions of their shares being offered through an OKX platform backed by ICE. The dispute illustrates a broader market reality: turning a security into an on-chain representation can involve securities rights, issuer permissions and market-structure questions that the technology alone does not solve.
That is relevant to XRPL's tokenization ambitions, even though the reported dispute does not establish direct Ripple or XRPL participation. Progress will rely on recognized legal ownership, compliant market access and trustworthy custody as much as ledger capabilities.
The Institutional Stack Is Taking Shape
Taken together, the announcements show how Ripple is assembling complementary financial infrastructure: regulated custody and fiduciary services, RLUSD for dollar-denominated movement, Ripple Treasury for corporate workflows, and XRPL for tokenized assets. These are distinct components serving different use cases.
XRPL adoption is not synonymous with buying XRP, and growth in RLUSD supply is not automatic evidence of XRP value accrual. XRP's investment thesis becomes stronger when adoption can be tied to measurable XRP-denominated liquidity, bridging, collateral or other native use—not simply the number of institutions named in announcements.
Final Thoughts
The most important shift this week is the move from broad institutional ambitions toward identifiable operating structures: a federal trust charter, an asset manager committing capital to an XRPL-based share class, and treasury software designed around round-the-clock finance. The next test is measurable use at scale.
Partner spotlight
Crypto and precious metals for your retirement
Buy XRP, XLM, gold & silver in a tax-advantaged IRA.
$100 funding bonus when you open and fund a new IRA or PCA.*
Get started*Terms and conditions apply.
Sources
https://ripple.com/ripple-press/ripple-receives-final-occ-approval-to-establish-national-trust-bank/
https://www.occ.gov/news-issuances/bulletins/2026/bulletin-2026-50.html